

National General

- 1.84K Reviews
- 4.6
- Downloads
- 500,000+
Our take on National General from Appgk
Choosing an insurance app is less about finding the most exciting download and more about deciding whether it will make an ordinary insurance task easier when you are busy, away from home, or dealing with a stressful situation. I spent time looking at National General as a mobile finance app, and my impression is that it is aimed at people who want their insurance relationship available from a phone instead of relying on a browser, a paper folder, or a call for every small question. That focus makes it practical, but it also means its value depends heavily on whether you already use National General for your insurance.
National General is developed by National General Insurance and is free to install. It is suitable for everyone from an age-rating perspective, runs on Android 9 or later, and has reached more than 500 thousand installs. The app has a 4.6 average from around 5 thousand ratings, with roughly 2 thousand written reviews, so it has attracted a meaningful audience rather than being an obscure companion app. Its current version is 1.90.778, and it was released on November 7, 2022.
What I would consider before choosing it
Start with the relationship, not the feature list
The first decision is straightforward: are you a National General customer, or are you looking for a general-purpose way to compare and manage insurance from different companies? This app is built around National General’s own insurance experience. That is useful when your policy, account information, and support needs already belong there. It is not a neutral insurance wallet that brings unrelated providers together.
That distinction matters more than the free price. A free app can still be the wrong tool if it does not connect to the policy you actually need to manage. In my view, existing customers should judge it by convenience: can it reduce the number of times they need to search for documents, remember account details, or move between separate services? People shopping across insurers should instead judge whether they need a provider-specific app at all.
Best Parts of National General
Things to Keep in Mind About National General
The second decision is how often you handle insurance away from a desk. Someone who only checks a policy once a year may be perfectly comfortable with a web account or printed documents. Someone who drives regularly, shares a vehicle with family, or needs quick access while traveling has more to gain from keeping insurance information close at hand. The app’s central appeal is availability, not entertainment or broad financial planning.
Think about the moments when insurance becomes urgent
Insurance apps are most valuable when the user is already under pressure. A minor collision, a request for policy information, or a question from another driver is not the ideal time to remember where a document was saved. I would therefore evaluate National General by asking whether it gives me a calmer starting point than my usual alternative. Even a simple mobile account can be worthwhile if it keeps the relevant insurance relationship easier to reach.
News and Features Related to National General

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
There is also a privacy and device question. A phone is convenient, but it is personal and sometimes shared. Before relying on any insurance app, I would use the phone’s normal security protections and avoid leaving sensitive account information visible on an unlocked screen. That is not a criticism unique to this app; it is the trade-off of putting financial and insurance access on a mobile device.
What the audience numbers suggest, and what they do not
The app’s average rating of 4.6 indicates that many users find the overall experience satisfactory. I would treat that as encouraging rather than conclusive. Ratings describe broad sentiment, while your own experience will depend on your policy, phone, login situation, and the task you are trying to complete. The written review count, at about 2 thousand, gives prospective users more context than a rating alone, but no score can guarantee that every account interaction will feel smooth.
Don't want to read the full review?
Because the app is marked for everyone, it is approachable from an age-classification standpoint. That does not make it a children’s product; insurance remains an adult responsibility involving personal and financial information. I see the rating as a sign that the app does not depend on mature entertainment content, not as a reason to hand account access to someone who should not manage the policy.
A realistic everyday scenario
Imagine that I am away from home and need to confirm insurance information after a low-speed parking-lot incident. My first reaction would probably be stress, followed by a search through email, photographs, or a glove-box folder. Having the insurer’s app already installed gives me one more direct route to my account. I would open it, sign in if necessary, look for the information relevant to the situation, and then contact the appropriate support channel if the issue required personal assistance.
Screenshots
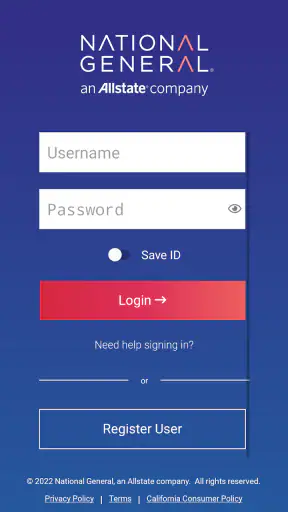
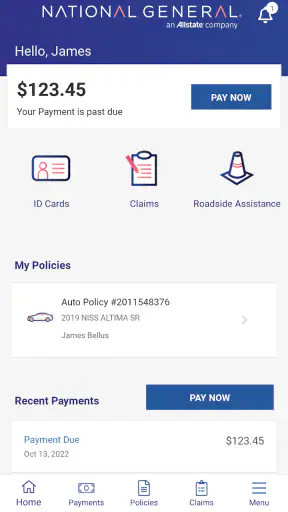
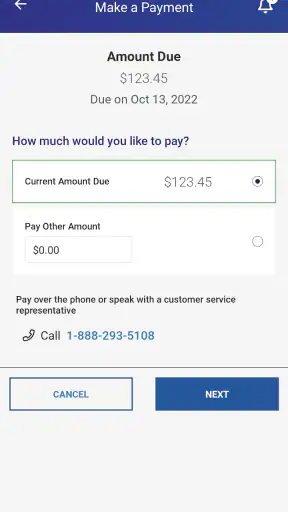
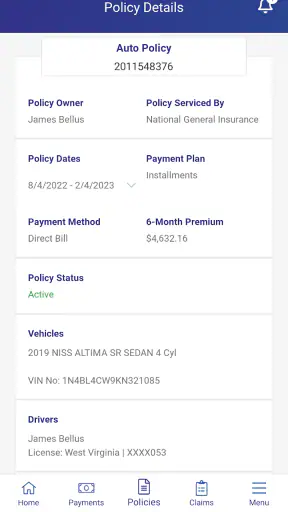
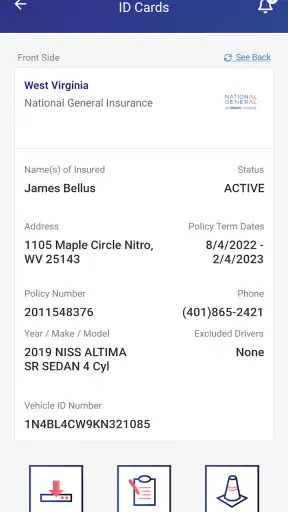
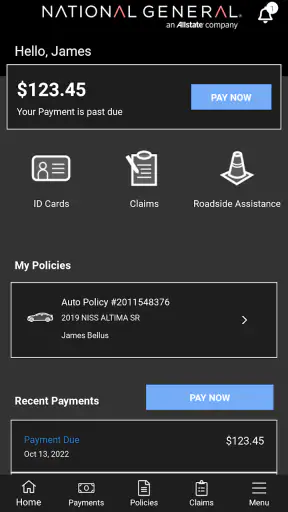
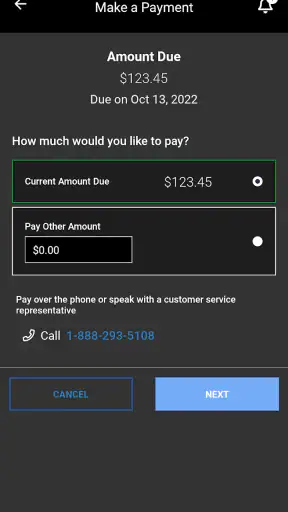
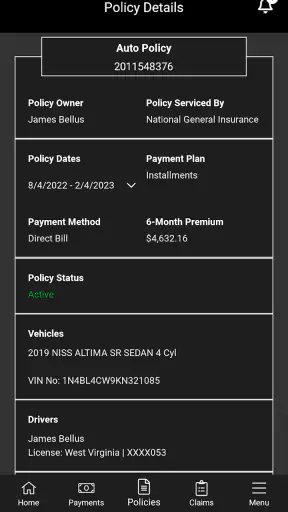
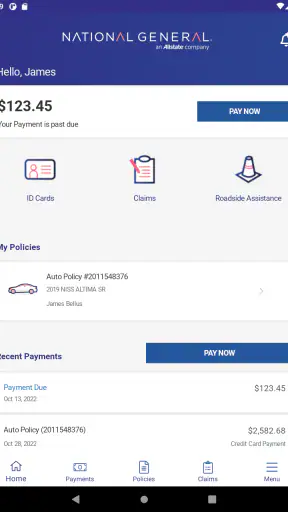
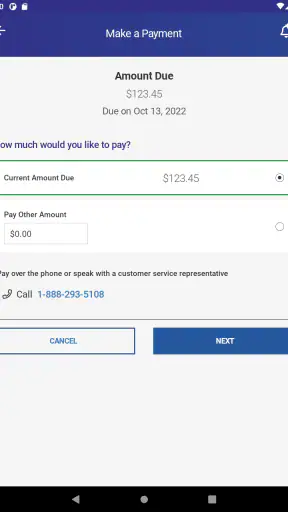
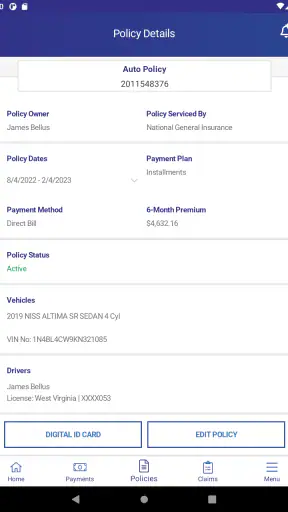
The important benefit in that scenario is not that a phone replaces every insurance conversation. It is that I do not begin with a blank search. I can use the app as a first stop, then move to human help when the matter is complicated. That division of labor is realistic: mobile access is excellent for retrieving account-related information, while unusual claims, disputes, or coverage questions may still need a representative who can understand the details.
Where National General makes the strongest case
A focused home for existing customers
The clearest strength is focus. National General is not trying to be a broad budgeting dashboard, a comparison marketplace, or a general personal-finance tracker. It is a dedicated connection to one insurance provider. For a customer who wants insurance available at any time, that narrow purpose can be more useful than a crowded finance app filled with unrelated tools.
I also like the psychological simplicity of having a recognizable place for insurance tasks. When an app is tied to the provider I already know, I do not have to wonder which third-party service has access to the account or whether a document belongs to the current policy. That does not remove the need to check details carefully, but it can reduce the clutter that builds up when insurance information is spread across messages, downloads, and paper records.
Useful as a backup to traditional documents
I would not treat the app as the only place where important insurance information exists. Phones can run out of power, connections can be unreliable, and login problems happen. Its better role is as a convenient backup to documents and other account access. Keeping a sensible offline record of essential information remains wise, especially before a long trip or when someone else may need to help with a vehicle.
This is one of the less obvious trade-offs. The app makes information more reachable, but mobile reachability is not the same as permanent availability. A careful user can benefit from both: use National General for quick access and routine account handling, while retaining a separate emergency record that does not depend on the app being open at that exact moment.
A sensible fit for recurring insurance housekeeping
Insurance is easy to ignore until something changes. A dedicated app can encourage better housekeeping because the account is visible in the same place where I already manage other phone-based tasks. I would use that convenience to review information after moving, changing vehicles, adding a driver, or updating contact details, rather than assuming an old record is still correct.
The app is also more appealing for people who dislike making a phone call for every straightforward matter. If the task is routine and account-based, a mobile route may feel less disruptive than waiting for business hours or searching through a website. That said, I would not confuse reduced friction with reduced responsibility. I would still read confirmations carefully and keep records of meaningful changes.
Three practical habits that improve the experience
Install and sign in before an urgent situation occurs. Testing access while calm is much better than discovering a forgotten password beside a damaged vehicle.
Keep the app updated through the normal app-store process. The current version is 1.90.778, and staying current is a sensible way to avoid using an outdated build when you need it.
Use the app alongside a simple emergency note containing the key contact and policy details you personally need. This gives you a fallback if the phone is offline, damaged, or being used by someone who does not normally sign in.
These habits are not flashy features, but they are where a provider app becomes genuinely useful. The value comes from preparation and repeatable routines, not from downloading it and forgetting it exists.
Where the current version fits in the decision
The release history and current version tell me that this is an established app rather than a brand-new experiment. I would still avoid assuming that every phone behaves identically after an update. Android 9 is the minimum operating system, which gives it a reasonably broad compatibility range for people who keep older devices. If your phone is older than that requirement, compatibility becomes a practical barrier before you can judge the app itself.
For supported devices, I would update at a convenient time and then open the app once to make sure the sign-in path and account access still work as expected. That small check is especially worthwhile before travel. It is a better workflow than waiting for a roadside problem to become the first real test of a newly updated app.
Why the free price still deserves a careful look
There is no purchase price for the app, which removes one obvious barrier. The more important cost is attention: learning another account, maintaining access, and deciding whether it genuinely replaces a slower method you already use. If I rarely need insurance information, the free download may still sit unused. If I regularly manage policy details, the convenience can justify keeping it on my phone.
I would also separate the app’s price from the cost of insurance itself. Free access to a mobile tool does not mean the underlying policy is free, cheaper, or automatically better. The app should be judged as a service companion, not as a reason to choose a policy without comparing coverage, suitability, and the terms that matter to your situation.
When another approach may fit better
People comparing several insurance providers
If I were still comparing insurers, I would not make National General’s app the deciding factor. A polished provider app cannot compensate for coverage that does not suit me, an unsuitable deductible, or a poor fit for my driving and household needs. In that stage, I would use broader comparison methods and examine the policy itself first. The app becomes relevant after the provider relationship is a serious option.
A multi-provider household may also prefer a more general organizational system. If different vehicles or family members are insured through different companies, a single provider app will not consolidate everything. In that case, a secure document system or a carefully maintained personal record may be easier than switching among insurer-specific apps. National General can still handle its own policy, but it will not remove the wider organizational problem.
People who prefer human support for every task
Some customers simply feel more comfortable speaking with an insurance representative. If I wanted advice about a complicated change, had trouble understanding coverage, or needed help with an unusual claim, I would not force the app to do a job it was not designed to replace. The strongest use case is quick access and routine account interaction; complex judgment still benefits from a person who can ask follow-up questions.
This is where expectations matter. A provider app should shorten the path to useful information, not promise that every situation becomes self-service. If you dislike digital sign-ins, do not want insurance information on your phone, or prefer a long conversation before taking action, traditional support may be the better primary channel. You can still keep the app as a backup, but you are unlikely to enjoy it as your main method.
People with unsupported or shared devices
The minimum operating system is Android 9, so anyone using an older Android phone should check compatibility before planning around it. Even on a supported phone, a shared device can create awkwardness around account privacy. I would be cautious about saving access on a phone used by several people, particularly when those users have different levels of responsibility for the policy.
There is also a practical accessibility consideration: a small screen and mobile interface may be less comfortable than a full browser for reading long policy information. I would use the app for quick checks, then choose a larger screen or direct support when I need to study detailed wording. Mobile convenience is strongest for short, focused tasks; it is not automatically the best format for every insurance document.
The cost of switching from your current routine
Moving from paper, email, or a browser to an app has a small learning cost. I would need to install it, establish access, recognize where information is located, and create a habit of checking the app rather than using an old bookmark. That effort is modest, but it is still real. If the current routine already works and I rarely touch insurance, switching may not produce a noticeable benefit.
On the other hand, the cost of not preparing can be higher during a stressful event. My preferred approach would be gradual: install National General, sign in at home, explore the account calmly, and keep the existing backup method for a while. After I know the app works for my needs, I can rely on it more often without discarding every other record immediately.
I would not uninstall a browser-based method just because the app is available. Accounts can behave differently across devices, and having a second route is useful if the phone is unavailable. The sensible switch is not an all-or-nothing move; it is adding a faster route while preserving a fallback until the new routine proves dependable.
Questions I would answer before relying on it
Can I use it without being a National General customer? I would not choose it on that assumption. Its purpose is tied to National General Insurance, so the meaningful experience is for people whose insurance relationship belongs with that developer. If you need a neutral tool for several companies, look for a different kind of solution.
Is it useful during an accident? It can be a helpful starting point for reaching your insurance account and organizing the next step, but I would not assume that an app alone handles every emergency or claim detail. I would prioritize safety, follow the instructions appropriate to the incident, and use the app as one part of the process rather than as a substitute for judgment or assistance.
Does free mean there are no insurance costs? No. The download price concerns the app, not the policy. I would compare the insurance product separately and never let mobile convenience make that decision for me.
Will it replace paper records? I would not recommend treating it as the only backup. Digital access is convenient, but a separate record can be valuable if the phone, account, or connection is unavailable. Keeping both options is a low-effort safeguard.
My recommendation for the right customer
My recommendation is positive but specific: National General is worth trying if you already use National General Insurance and want a direct mobile route to your insurance relationship. Its free availability, broad Android compatibility from version 9 onward, and established user base make it an easy app to test without committing to a new financial product. I would install it before I need it, confirm access, and keep a backup record for urgent situations.
I would skip it as a primary choice if I am shopping among insurers, managing policies from several providers, or expecting a general finance app to consolidate every insurance account. I would also choose direct human support for complicated coverage decisions or situations where a conversation matters more than speed. Those are not failures of this particular app; they are signs that a provider-specific mobile companion is not the right category for the job.
In the end, I see National General as a practical convenience layer rather than a reason to change insurers. It earns its place on my phone when it reduces searching and makes routine insurance access less awkward. If that is the problem you want to solve, it is a sensible, focused option. If your real problem is comparing policies or coordinating several companies, I would spend my effort elsewhere first.
National General FAQ
What is the National General app used for?
The National General app is designed to help policyholders manage their insurance information from a mobile device. Depending on your policy and account, you may be able to view coverage details, access digital insurance documents, make payments, review billing information, request assistance, and contact customer support. Available features can vary by state, policy type, and whether your account is fully registered.
How do I log in or create a National General account?
To use the app, you generally need an active National General policy and the login details associated with your online account. New users can usually register by providing identifying information requested by the service, such as policy details and contact information. Make sure your personal information matches the policy records, and use the password recovery option if you cannot remember your credentials.
Can I make an insurance payment through the National General app?
In many cases, the National General app allows eligible customers to review billing information and make insurance payments using an available payment method. Before confirming a transaction, carefully check the amount, due date, and selected policy. Payment options and processing times may differ depending on your policy, state, account status, and the payment method you choose.
Can I access my insurance ID card and policy documents in the app?
The app may provide digital access to important documents, including insurance identification cards, policy information, and billing records. This can be convenient when you need to show proof of coverage while traveling or handling a vehicle-related matter. However, document availability can depend on your policy and account, so keep a current copy available if required in your area.
Is the National General app suitable for reporting a claim or requesting roadside help?
The app may offer tools for starting or managing certain claims and contacting assistance, but the exact services depend on your coverage and policy terms. Before relying on the app during an emergency, confirm that your plan includes the relevant service and follow the instructions shown on screen. For urgent situations, contact emergency services first when necessary.













